FEMA resilience grants dropped from $3.3 billion in 2022 to $726 million in 2025. The bill for flood and storm defenses is moving to states, cities and the businesses that depend on them, through a bond market that still barely discloses climate risk.
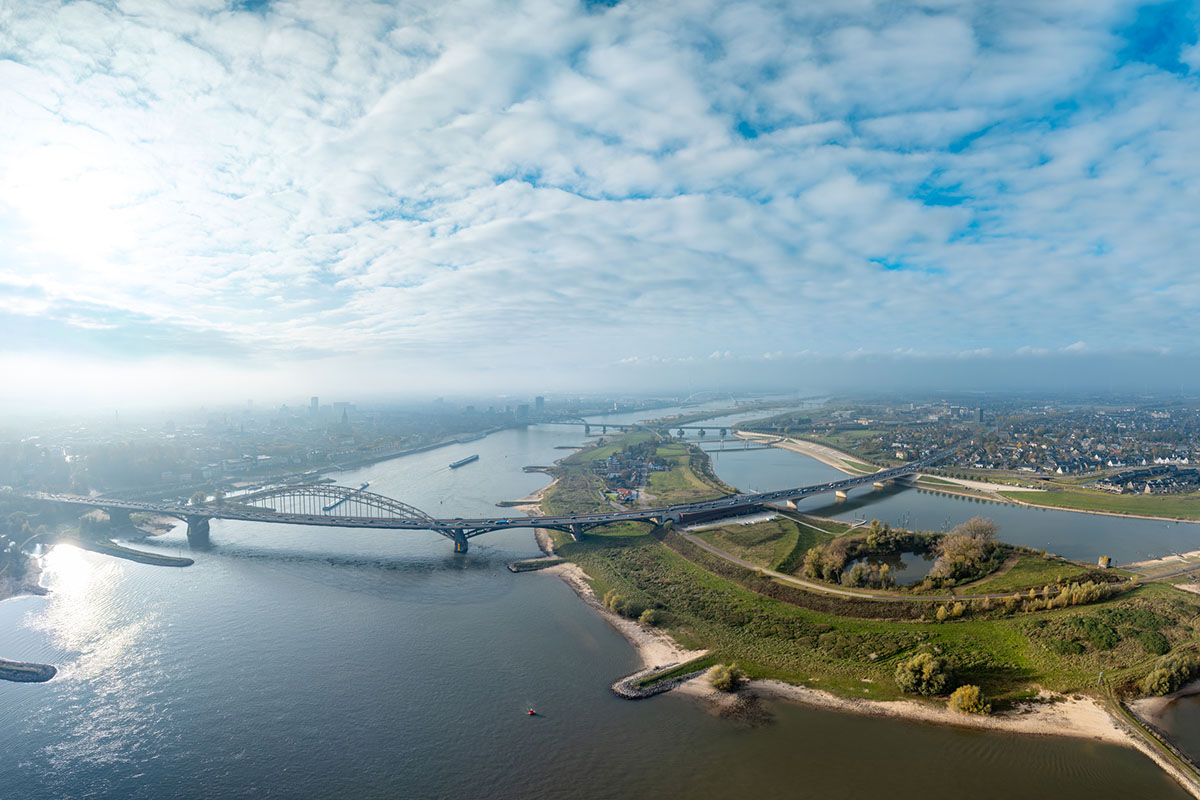
Key Takeaways
For years, the quiet assumption behind corporate climate risk planning in the United States was that someone else would pay for the levee. Federal grants funded the flood walls, culverts and buyouts that protect the towns where companies run plants, warehouses and data centers. That assumption no longer holds. Federal resilience funding has fallen by more than three quarters in three years, and the cost is landing on state and local balance sheets, and through them on every business that pays local taxes or depends on local infrastructure.
A September 28 analysis from Resources for the Future tracks the decline program by program. FEMA awarded $3.3 billion in resilience grants in fiscal 2022, 68 percent of it through the Building Resilient Infrastructure and Communities (BRIC) program. By fiscal 2025 the total was $726 million, most of it retroactive BRIC money. The authors, Sofia Hines and Margaret Walls, describe the drop in fiscal 2025 and 2026 as "obvious."
The path there was abrupt. The administration announced the end of BRIC in April 2025 and retracted $3 billion for projects that had already been approved. Twenty states sued, and a federal judge ordered the program restored. Flood Mitigation Assistance, which pays to protect properties insured under the National Flood Insurance Program, lost $600 million in retracted funding, with no new money announced for fiscal 2024, 2025 or 2026. BRIC's direct technical assistance for underserved communities was eliminated in March 2026, and FEMA removed public access to planning tools including its Future Risk Index.
Grants have not stopped entirely. In a September 18 press release, FEMA announced nearly $180 million in mitigation funding, including more than $160 million through the Pre-Disaster Mitigation program for 115 projects in 39 states and one Tribal Nation, most of them aimed at flood risk. Set against $3.3 billion four years earlier, it is a top-up, not a replacement. The RFF authors put the consequence bluntly: state and local governments are now "on their own" in paying for resilience and working out how to proceed.
When federal grants recede, local governments borrow. Researchers at Northeastern University, writing in Nature Cities, note that municipal bonds already finance more than 70 percent of US public projects, with about $500 billion issued each year. Tom Doe of Municipal Markets Analytics expects issuance to reach $1 trillion a year in the 2030s, largely because of resilience and adaptation projects. The same researchers warn of a "climate debt doom loop," in which physical losses weaken municipal finances, limit adaptation spending, raise future exposure and push borrowing costs higher still.
The problem is that investors are being asked to fund this shift with very little information. In August, The Bond Buyer reported on a Ceres review of 60 recent municipal bond offerings across 20 climate-exposed US metro areas. A third made no mention of climate or extreme weather risk at all. Only 12 percent included quantitative metrics or targets for managing climate risk, and just 15 percent said who in government was accountable for it. Ceres also found that many municipalities do invest in resilience but leave that spending out of their offering documents, so investors cannot price the risk reduction they are paying for.
A relatively mild year for losses makes the gap easy to ignore. Aon's first-half review found global economic losses 25 percent below the 21st-century average, yet the United States still accounted for about 75 percent of global insured losses, roughly $36 billion, with 11 separate billion-dollar insured events, nine of them severe convective storm outbreaks. A quiet half-year is not a reason to defer the defenses that federal money used to fund.
Companies feel the federal retreat in three ways. Local taxes and fees rise as municipalities borrow to replace lost grants. Projects that would have protected a facility's road access, power supply or drainage get delayed or shelved. And the physical risk at each site goes up while the public data that used to help quantify it becomes harder to reach. For companies that report climate-related financial risk, whether to investors, under CSRD or ahead of California's SB 261, the resilience of host communities is now part of their own risk profile.
There is also an opportunity. Public issuers that can show measurable resilience spending will reach investors more cheaply, and companies that co-invest with host communities can shape which projects get built first. The playbook looks like this:
The federal government has stepped back from paying for resilience, but the floods and storms have not. The cost is moving to local governments and the companies that rely on them, and the organizations that measure that exposure now will decide where the scarce money goes next.
Scorecard
With federal mitigation grants shrinking, local finance teams must fund resilience from their own budgets and borrowing. This self-assessment helps them benchmark financial resilience and decide where to invest first.
Download
Report
When the flood wall a site relied on is delayed, staying operational becomes the company's own job. This report examines what separates organizations that ride out crises and the technology investments behind them.
Download
Guide
Host-community resilience now belongs in a company's climate-related financial risk picture. This starter kit helps companies doing business in California build a credible 90-day plan for their climate reporting obligations.
Download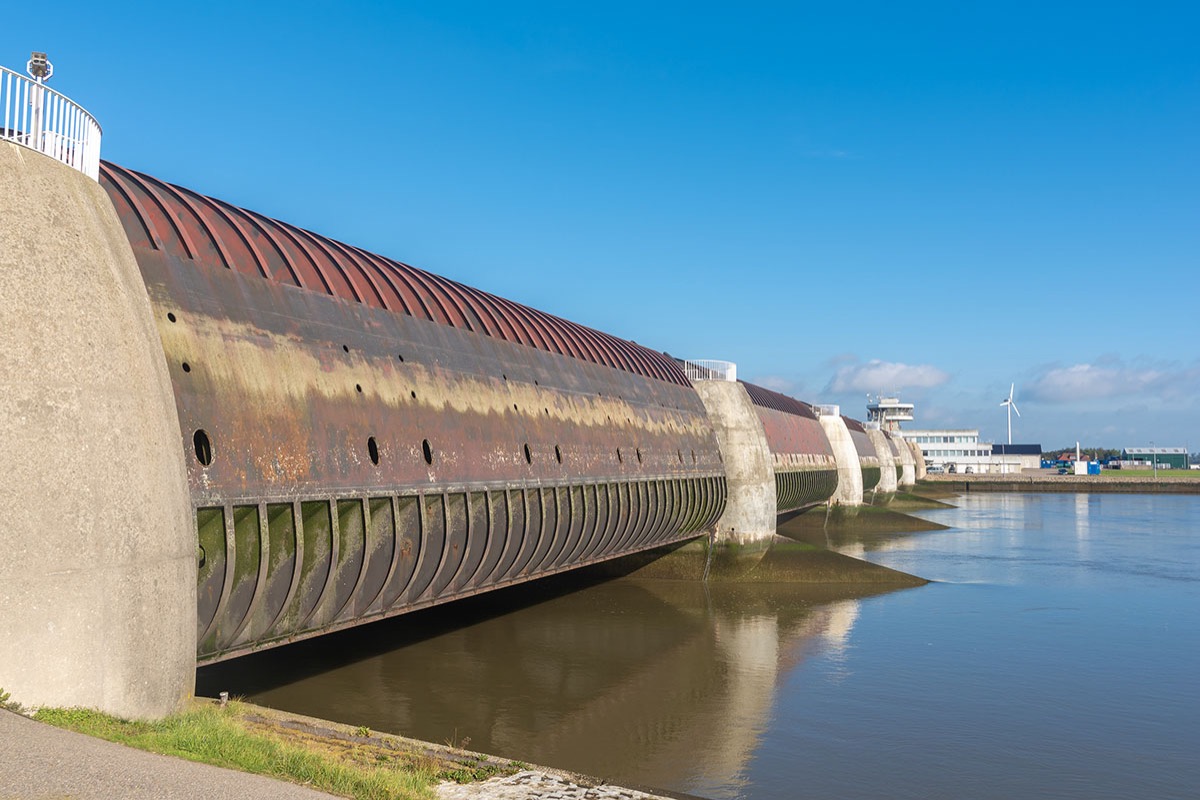
Schroders and CalPERS have built a framework to price adaptation as an investable market, and New York just sold its first ESG-labeled general obligation bonds. The money moving is still a fraction of what is needed.
The sustainable debt market reached a new milestone, but credibility gaps are widening. Investors are demanding stricter use-of-proceeds standards and independent verification before committing capital to labelled instruments.
